Skip to content

Tax Efficiency Lab

  • Home
  • Guides
  • About
  • Affiliate Disclosure
  • Privacy & Terms
  • Contact

O. Nevokhel

Australia Tax Guide 2026: Income Tax, CGT, Superannuation and Residency Explained
10/17/202607/26/2026 by O. Nevokhel
Sydney Opera House and Harbour Bridge illuminated at night, Australia

Australia tax guide for 2026-27: income tax bands, 30%/25% company tax, CGT discount, franking credits, Div 296 super tax, GST and residency explained.
Categories Australia, Tax Guides

Seychelles Tax Guide 2026: Territorial Taxation, Business Tax and Residency Explained

10/17/202607/18/2026 by O. Nevokhel
Granite boulders and turquoise water on La Digue, Seychelles

Seychelles tax guide for 2026: territorial taxation, 0% on foreign income, 15-25% business tax, no capital gains or inheritance tax, residency explained.
Categories Seychelles, Tax Guides

Italy Tax Guide 2026: The €300,000 Flat Tax, IRPEF Bands and Residency Rules Explained

10/17/202607/18/2026 by O. Nevokhel
Positano on the Amalfi Coast, Italy

Italy tax guide for 2026: new €300,000 flat tax for wealthy new residents, 23-43% IRPEF bands, impatriate reliefs and inheritance rules explained.
Categories Italy, Tax Guides

Indonesia Tax Guide 2026: Progressive Rates, the Expat Territorial Regime and Residency Explained

10/17/202607/18/2026 by O. Nevokhel
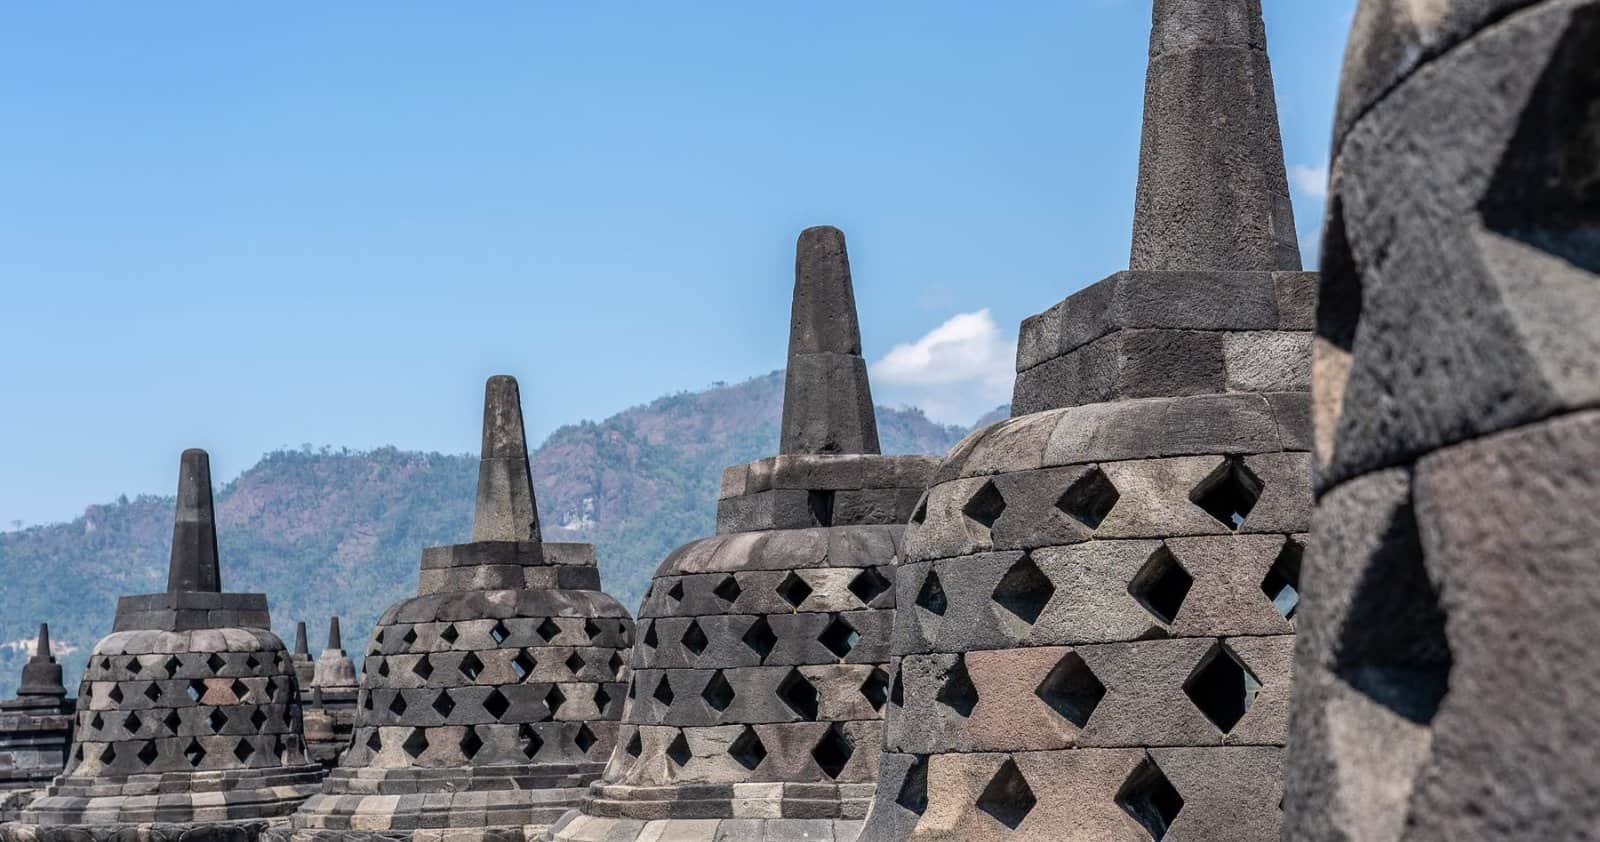
Stupas of Borobudur temple in Java, Indonesia

Indonesia tax guide for 2026: 5–35% income bands, 22% corporate tax, 11–12% VAT, the 4-year expat territorial regime and 183-day residency explained.
Categories Indonesia, Tax Guides

Thailand Tax Guide 2026: Foreign Income Remittance Rules, LTR Visa Exemptions and Residency Explained

10/17/202607/11/2026 by O. Nevokhel
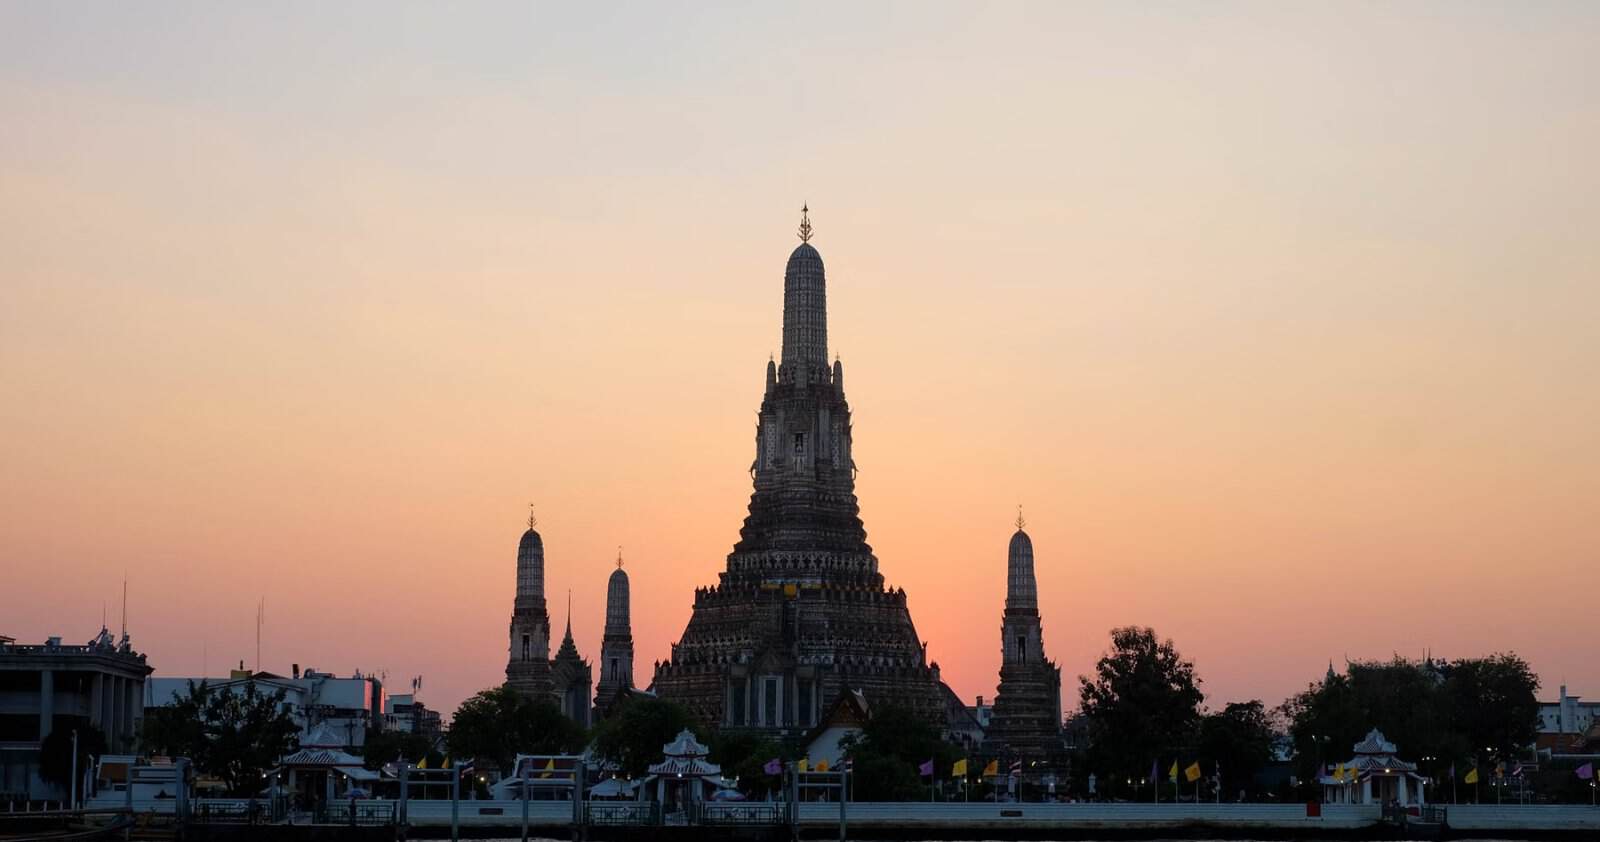
Wat Arun temple at sunset in Bangkok, Thailand

Thailand tax guide for 2026: 0–35% income bands, foreign income remittance rules, LTR visa exemptions, 7% VAT and the 180-day residency test explained.
Categories Tax Guides, Thailand

Malta Tax Guide 2026: Non-Dom Remittance Basis, 5% Effective Corporate Tax and Residency Explained

10/17/202607/11/2026 by O. Nevokhel
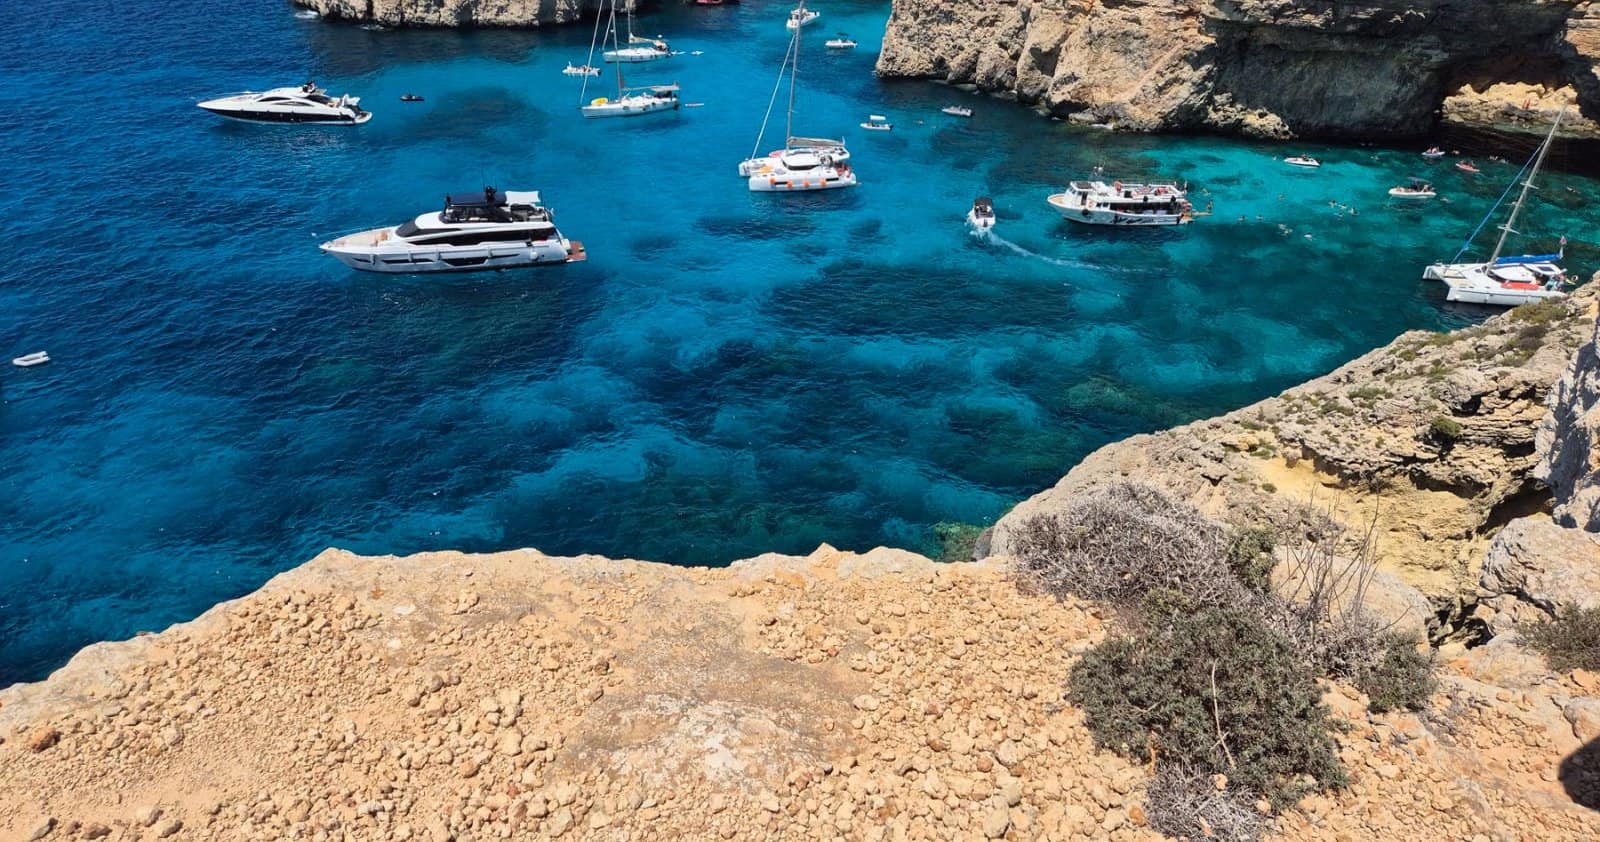
The Blue Lagoon at Comino, Malta

Malta tax guide for 2026: 0–35% income bands, 5% effective corporate tax via refunds, non-dom remittance basis, no wealth or inheritance tax explained.
Categories Malta, Tax Guides

Bahamas Tax Guide 2026: Zero Income Tax, 10% VAT and Residency Explained

10/17/202607/11/2026 by O. Nevokhel
A beach gazebo on a Bahamian shore

Bahamas tax guide for 2026: no income, capital gains or inheritance tax, 10% VAT, property tax bands, the new 15% minimum tax and residency explained.
Categories Bahamas, Tax Guides

Mauritius Tax Guide 2026: 15% Rates, Remittance Basis and Residency Explained

10/17/202607/05/2026 by O. Nevokhel
A catamaran on a turquoise lagoon in Mauritius

Mauritius tax guide for 2026: 10–20% income tax, 15% corporate rate, 3% on exports, no capital gains or inheritance tax, and residency routes explained.
Categories Mauritius, Tax Guides

Monaco Tax Guide 2026: Zero Income Tax, Business Profits Tax and Residency Explained

10/17/202607/05/2026 by O. Nevokhel
Monaco harbour illuminated at dusk

Monaco tax guide for 2026: 0% personal income tax, 25% business profits tax, no capital gains or wealth tax, inheritance rules and residency explained.
Categories Monaco, Tax Guides

Andorra Tax Guide 2026: 10% Flat Taxes, IGI and Residency Rules Explained

10/17/202607/05/2026 by O. Nevokhel
Andorra set against the Pyrenees mountains

Andorra tax guide for 2026: 10% income and corporate tax, 4.5% IGI, no wealth or inheritance tax, capital gains rules and residency options explained.

Categories Andorra, Tax Guides
Older posts
Newer posts
← Previous Page1 … Page3 Page4 Page5 Page6 Next →
© 2026 Tax Efficiency Lab • Built with GeneratePress
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}