This Isle of Man tax guide covers the rules in force from 6 April 2026. Personal income tax runs at 10% and 21% behind a personal allowance of £17,000 (~$23,000), and a resident can cap total income tax at £220,000 (~$297,000) a year. Companies pay 0% on most trading and investment income, with 10% on banking and large retail and 20% on Manx land and property. There is no capital gains tax, no inheritance tax, no wealth tax and no stamp duty. VAT is 20% under a single territory shared with the UK.
Introduction
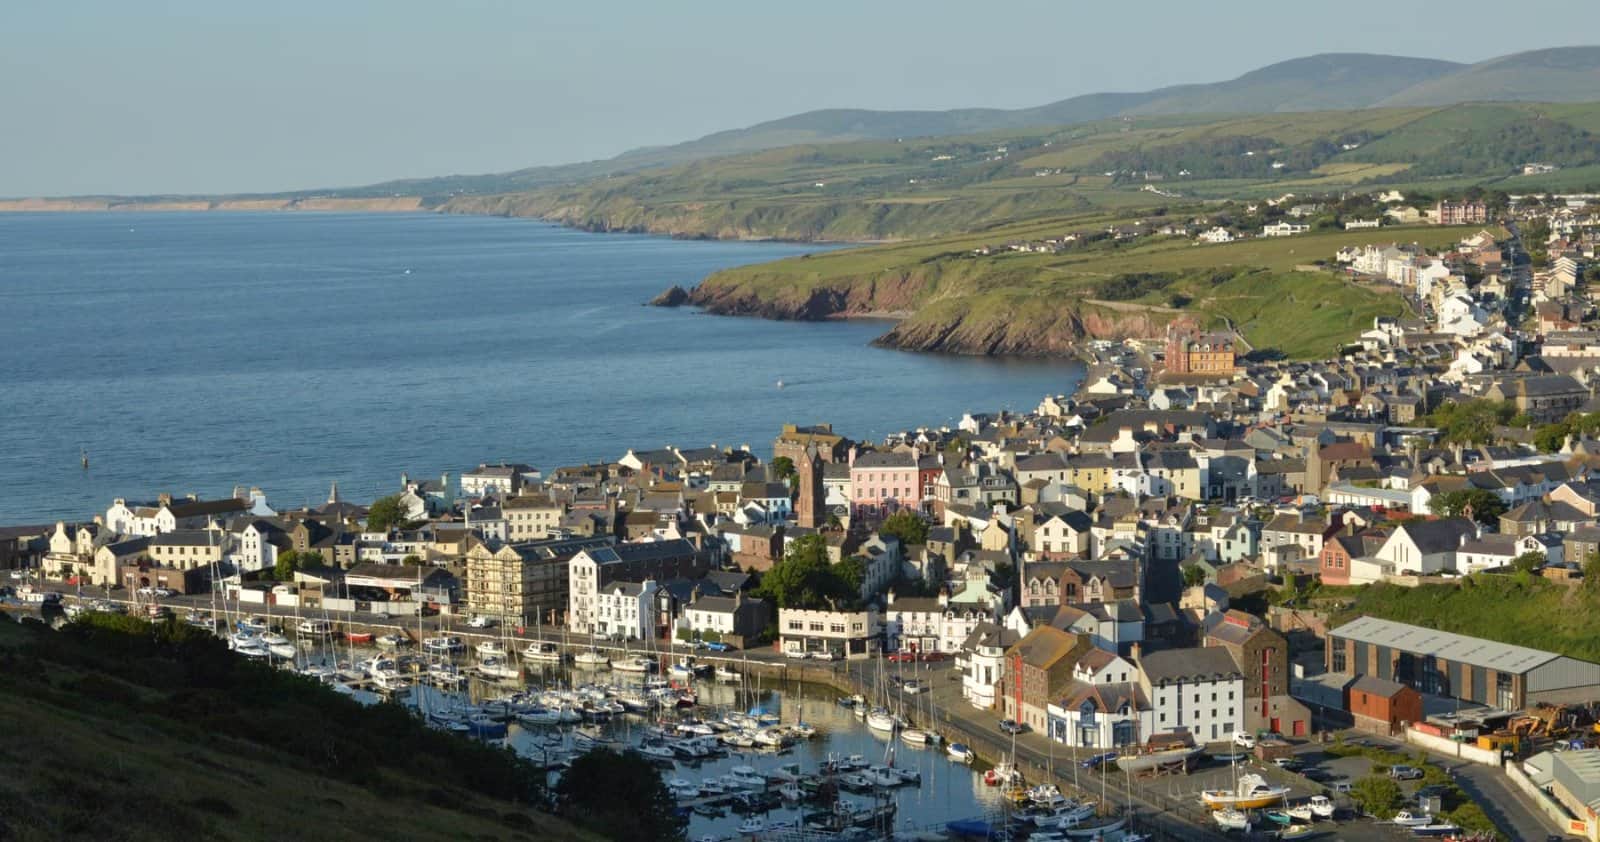
The Isle of Man is a self-governing British Crown Dependency of roughly 85,000 people in the Irish Sea, midway between Britain and Ireland. It is not part of the United Kingdom and not part of the European Union, but sits inside the Common Travel Area and inside a customs and VAT union with the UK. Tynwald, its parliament, sets tax law independently of Westminster. The legal system is Manx common law drawing heavily on English precedent, the language is English, and the currency is the Manx pound, issued by the Isle of Man Treasury and equivalent in value to sterling. The climate is mild, damp and maritime; Douglas is the capital and the centre of the financial sector; living costs track prosperous UK regions, with housing the pressure point.
This Isle of Man tax guide matters because the Island pairs a 0% headline corporate rate with a fully-functioning onshore system — treaty access, a UK-aligned VAT regime, OECD-endorsed Pillar Two legislation and a real economy in insurance, fund administration, e-gaming, shipping and aircraft registration. For individuals the draws are the absence of capital gains and inheritance taxes, a top rate of 21%, and the tax cap, an election that fixes the annual income tax bill at £220,000 (~$297,000) however much is earned. The 2026 Budget, delivered on 17 February 2026, raised the personal allowance by £2,250 (~$3,000) and held the higher rate at 21%, already cut from 22% in 2025/26.
Direct Taxes
Residents are taxed on worldwide income from all sources; non-residents only on Manx-source income, with exemptions for most bank interest and dividends. There is no remittance basis and no non-dom regime — residence is the single switch. Progressivity is shallow: an allowance, one narrow 10% band, then a flat 21% above it, with the whole liability optionally capped. Companies are resident if incorporated in the Island or, if incorporated abroad, managed and controlled there. The signature concept for investors is not a preferential regime but the standard 0% corporate rate, which applies by default and is fenced only by sector carve-outs, economic substance rules and Pillar Two.
Personal income tax (2026/27 bands)
| Chargeable income (£, USD) | Rate |
|---|---|
| Personal allowance — first £17,000 (~$23,000) single / £34,000 (~$45,900) jointly assessed | 0% |
| Next £6,500 (~$8,800) single / £13,000 (~$17,600) jointly assessed | 10% |
| Balance above that | 21% |
| Non-residents — all taxable Manx income (no allowance) | 21% |
| Tax cap election — maximum annual liability | £220,000 (~$297,000) single / £440,000 (~$594,000) jointly assessed |
These bands apply for the year of assessment beginning 6 April 2026. They replace 2025/26 allowances of £14,750 (~$19,900) and £29,500 (~$39,800), and a higher rate that stood at 22% as recently as 2024/25. The allowance is withdrawn by £1 for every £2 of income above £100,000 (~$135,000), or £200,000 (~$270,000) jointly, disappearing entirely above £134,000 (~$181,000) single. Targeted reliefs include mortgage and loan interest up to £5,000 (~$6,800) single or £10,000 (~$13,500) jointly, nursing expenses up to £15,000 (~$20,300), charitable donations up to £7,000 (~$9,500), private medical insurance up to £1,800 (~$2,400) and a benefit-in-kind exemption of £600 (~$800). The tax cap election runs for five or ten consecutive tax years and is binding for the period chosen.
Corporate income tax
| Item | Rate |
|---|---|
| Standard corporate income tax — all companies, resident and non-resident | 0% |
| Banking business (FSA deposit-taking licence) | 10% |
| Retail business — profits above £500,000 (~$675,000) | 10% |
| Income from Isle of Man land and property | 20% |
| Petroleum extraction activities or rights (from 6 April 2024) | 20% |
| Voluntary election by a 0% company | 10% |
| Pillar Two Domestic Top-up Tax / Multinational Top-up Tax (from 1 January 2025) | 15% |
| Temporary rate for in-scope banking and large retail (2024/25 only) | 15% |
The Global Minimum Tax (Pillar Two) Order 2024, approved by Tynwald in November 2024 and amended twice in 2025, applies a 15% Domestic Top-up Tax and a Multinational Top-up Tax to groups with consolidated revenue of €750 million (~$870 million) or more in at least two of the four preceding years, for fiscal years beginning on or after 1 January 2025. The DTUT is built to qualify for QDMTT safe-harbour status and the MTUT for Qualified IIR status, both endorsed by the OECD; a de minimis exclusion removes the DTUT where average Manx GloBE revenue is under €10 million (~$11.6 million) and average income under €1 million (~$1.16 million). Below that threshold the 0% rate is untouched. There is no withholding tax on dividends to residents or non-residents and generally none on interest or royalties, though 20% is withheld on rent from Manx property paid to non-residents. Economic substance rules have applied since accounting periods beginning 1 January 2019 across nine sectors — banking, insurance, shipping, fund management, financing and leasing, headquartering, holding companies, intangible property and distribution and service centres — with fines, information exchange and ultimately strike-off for non-compliance.
Social security and health contributions
| Contribution | Employee | Employer | Self-employed |
|---|---|---|---|
| Class 1 — main rate | 11% on earnings between £176 (~$238) and £1,082 (~$1,460) per week | 12.8% on all earnings above £176 (~$238) per week | — |
| Class 1 — above upper earnings limit | 1% | 12.8% (no ceiling) | — |
| Class 2 — flat weekly | — | — | £6.75 (~$9.10) per week, £351 (~$474) a year |
| Class 4 — on profits | — | — | 8% between £9,152 (~$12,400) and £56,264 (~$76,000); 1% above |
| Class 3 — voluntary | £20.65 (~$27.90) per week | — | — |
The employee ceiling is soft: the rate drops from 11% to 1% above £1,082 (~$1,460) a week, but contributions never stop. The employer 12.8% has no ceiling at all — the largest hidden cost of putting yourself on a Manx payroll rather than taking dividends. The lower earnings limit is £129 (~$174) a week and the Class 2 small earnings exception £9,152 (~$12,400). There is no separate health levy; the Manx health service is funded from general revenue. The National Insurance Holiday Scheme, which refunded up to £4,400 (~$5,900) of Class 1 contributions to qualifying new arrivals earning at least £23,000 (~$31,100), closed to new residents on 6 April 2025 and now runs only for returning Manx students.
Indirect Taxes
The Isle of Man forms a single VAT and customs territory with the United Kingdom under the Customs and Excise Agreement, and Manx VAT law is broadly identical to UK law. Registration runs through Isle of Man Customs and Excise, but a Manx VAT number functions as a UK number for trade. VAT is the largest indirect tax and, through the revenue-sharing arrangement with the UK, a large share of government income.
Value-added tax (VAT)
| Rate | Applies to (examples) |
|---|---|
| 20% (standard) | Most goods and services |
| 5% (reduced) | Energy-saving materials, construction services on eligible buildings, domestic property repairs, children’s car seats |
| 0% (zero) | Most basic foodstuffs, children’s clothing, construction of new dwellings, books, public transport, exports |
| Exempt | Insurance, financial services, betting and gaming, education, healthcare, most land transactions |
Registration is compulsory once taxable turnover exceeds £90,000 (~$121,500) in a rolling twelve months, with voluntary registration below that — the threshold is not published on the Customs and Excise rates page, so verify it with the Division before relying on it. The 5% rate on domestic property repairs and renovations is a long-standing Manx divergence more generous than the UK equivalent.
Excise and other indirect taxes
| Tax | Notes |
|---|---|
| Excise duties | Alcohol, tobacco and hydrocarbon oils, broadly aligned with UK rates |
| Customs duty | On goods imported from outside the UK–Isle of Man territory |
| Online gaming duty (OGRA licensees) | Tiered on gross gaming yield: 1.5% up to £20 million (~$27 million), 0.5% from £20–40 million (~$27–54 million), 0.1% above £40 million (~$54 million). Land-based betting and pool betting duties are charged separately |
| Air passenger duty | On commercial passenger flights departing the Island |
| Local authority rates | Annual charge on residential and commercial property, set by each parish or town commission on rateable value |
| Stamp duty / land transfer tax | None — no stamp duty on property or share transfers |
Gambling duty is charged on gross gaming yield rather than turnover, which is why the Island is competitive for e-gaming before the 0% corporate rate is even considered. Local authority rates are modest by UK council tax standards, vary widely between authorities, and are the only recurring charge on owning a Manx home.
Other Taxes Worth Knowing
| Tax | Isle of Man treatment |
|---|---|
| Capital gains tax | None — no CGT on any asset class, for individuals or companies |
| Dividends (resident individual) | Taxable as income at 10% / 21%; covered by the tax cap if elected |
| Interest (resident individual) | Taxable as income at 10% / 21%; no separate savings rate |
| Rental income (Manx property) | Individuals: 10% / 21%. Companies: 20%. Non-residents: 20% withholding |
| Rental income (foreign property) | Resident individuals taxed at 10% / 21% with credit relief for foreign tax |
| Wealth / net worth tax | None |
| Inheritance / estate tax | None — no death duties or estate duties |
| Gift tax | None |
| Immovable property tax (annual) | Local authority rates only — no national property tax |
| Stamp duty | None |
| Capital duty / capital transfer tax | None |
| Withholding tax on dividends | 0% to residents and non-residents alike |
In practice a Manx resident holding a global securities portfolio pays 10% then 21% on dividends and interest, and nothing at all on realised gains — no annual exemption to track, no disposal reporting, no rebasing on arrival. Foreign tax suffered is relieved by credit, capped at the lower of the foreign tax and the Manx marginal rate, so withholding deducted abroad on dividends often exceeds what the Island would charge and becomes an absolute cost. That asymmetry, more than the Manx rates themselves, usually determines a portfolio’s effective rate.
Disadvantages & Risks
The Island is fiscally exposed in a way its headline rates conceal. A substantial share of government revenue arrives through the VAT revenue-sharing arrangement with the UK rather than from taxes Tynwald controls, and that formula has been renegotiated downwards before — the 2009 revision forced years of austerity. The economy is highly concentrated in financial services, insurance, fund administration and e-gaming, all sensitive to UK and EU regulatory shifts the Island does not vote on. The banking sector is small and consolidated: opening accounts as a new arrival, particularly for a company with non-resident owners, is slow and document-heavy. Housing is tight, prices have risen faster than incomes, and non-UK nationals need Isle of Man work permits granted on the Island’s own terms rather than the UK’s.
Reputationally the picture is better than the “tax haven” label suggests, but not risk-free. The Isle of Man appears on neither Annex I nor Annex II of the EU list of non-cooperative jurisdictions as updated on 17 February 2026, is not FATF grey-listed, and its Pillar Two legislation is OECD-endorsed. It is, however, mid-way through a MONEYVAL mutual evaluation: technical compliance questionnaire submitted March 2026, written effectiveness submission June 2026, on-site assessment scheduled for later in 2026 with the report to follow. A poor effectiveness rating would be the most consequential reputational event the Island faces this decade. Economic substance also bites harder than newcomers expect — a holding or IP company with no Manx directors, staff or premises will not survive scrutiny — and Pillar Two has already removed the 0% rate for the largest groups, so the headline advantage now has a defined ceiling.
Strategy & Ideal Profile
The structure that works is the simplest one: a Manx-incorporated company taxed at 0%, genuinely managed and directed from the Island with resident directors, real premises and proportionate local spend, distributing to a Manx-resident shareholder who pays 10% then 21% on the dividends. With no dividend withholding and no capital gains tax, profits can be extracted or the company sold with no second layer of Manx tax. Above €750 million (~$870 million) of consolidated group revenue that plan collapses into the 15% top-up, so this is a regime for owner-managed and mid-market businesses, not large multinationals. The tax cap then turns the Island into a fixed-cost jurisdiction: above roughly £1.06 million (~$1.43 million) of income the cap beats the 21% rate and the saving grows without limit, which is why the election runs five or ten years rather than annually.
It suits company owners who can relocate the mind and management of the business and want a 0% rate with treaty and UK market access rather than a nameplate offshore company. It suits investors and traders, because realised gains are untaxed outright — no holding period, no asset-class restriction, no annual exemption to manage. It suits very high earners whose income would otherwise produce more than £220,000 (~$297,000) of Manx tax. And it suits retirees and families with substantial estates, since the absence of inheritance, gift and wealth taxes makes intergenerational transfer a matter of company and trust law rather than tax. Residence is practical rather than mechanical: six months or more of presence in a tax year makes you resident, and the Assessor can treat shorter presence as residence where a home is kept available and visits are frequent and purposeful. There is no bright-line day count beyond the six-month test, so intending residents should seek a determination from the Income Tax Division rather than count days.
It does not suit anyone who must stay UK-resident: this is a relocation play, not a structuring overlay, and UK anti-avoidance rules reach a Manx company controlled from Britain. It does not suit large multinational groups, for whom Pillar Two has closed the gap. It does not suit those wanting Schengen or EU access — the Island is outside both, and the customs union with the UK confers no EU rights. And the headline benefit has limits worth pricing in: employer National Insurance at 12.8% is uncapped, Manx property income is taxed at 20% inside a company, and the tax cap is a Tynwald policy setting that has already moved once, from £200,000 (~$270,000) in 2024/25 to £220,000 (~$297,000) today.
FAQ
Is the Isle of Man a tax haven?
It is a low-tax jurisdiction rather than a secrecy jurisdiction. Most profits bear no corporate income tax and there is no capital gains or inheritance tax, but the Island operates the Common Reporting Standard and FATCA, enforces economic substance rules across nine sectors, and has implemented OECD Pillar Two. It appears on neither annex of the EU list of non-cooperative jurisdictions as at 17 February 2026 and is not FATF grey-listed.
What is the corporate tax rate in the Isle of Man in 2026?
The standard rate is 0% for resident and non-resident companies alike. Licensed banking business and retail profits above £500,000 (~$675,000) are taxed at 10%; Manx land and property income and petroleum extraction at 20%. Groups with consolidated revenue of €750 million (~$870 million) or more face a 15% Pillar Two top-up for fiscal years beginning on or after 1 January 2025. A 0% company may elect to be taxed at 10% if a treaty partner requires it.
How does the Isle of Man tax cap work?
A resident individual elects to cap total income tax at £220,000 (~$297,000) a year, or £440,000 (~$594,000) for a jointly assessed couple, whatever the income level. The election runs for five or ten consecutive tax years and is binding for that period. It pays above roughly £1.06 million (~$1.43 million) of taxable income, and the capped amount falls due on 6 January in each tax year of the election.
How do you become Isle of Man tax resident?
Presence for six months or more in a tax year — which runs 6 April to 5 April — generally makes you resident. Residence can also arise on shorter presence where you keep a home available for your own use and visit frequently; the Assessor of Income Tax weighs accommodation, frequency and purpose of visits rather than applying a single statutory day count. UK and Irish nationals move freely under the Common Travel Area; others need an Isle of Man work permit.
Does the Isle of Man tax capital gains?
No. There is no capital gains tax on any asset — shares, funds, property, crypto or business sales — for individuals or companies. Activity amounting to a trade rather than investment is taxed as trading income instead, meaning 10% then 21% for an individual and nothing for a 0%-rate company, so the trading-versus-investment line matters far less here than elsewhere.
Is there inheritance or wealth tax in the Isle of Man?
No. There are no death duties, no estate duty, no gift tax and no net wealth tax, and the estate of a Manx-domiciled individual bears no Isle of Man tax. Non-Manx assets can still be exposed to the inheritance tax of the country where they sit — UK-situs property in particular stays within the UK inheritance tax net regardless of the owner’s Manx residence.
How are dividends taxed for a non-resident investor?
Dividends paid by an Isle of Man company to a non-resident carry 0% withholding tax, and non-residents are generally not taxable on Manx dividends or most bank interest, leaving tax to the investor’s home jurisdiction. Rent from Manx land and property is the exception: 20% is withheld at source.
Sources
Every figure above should be checked against the primary government sources below. Only official bodies are listed.
- Isle of Man Government, Income Tax Division — personal income tax rates, allowances and the tax cap — gov.im
- Isle of Man Government, Income Tax Division — historic and current rates (2024/25–2026/27 comparison) — gov.im
- Isle of Man Government, Income Tax Division — corporate tax rates — gov.im
- Isle of Man Government, Income Tax Division — Pillar 2 Global Minimum Tax and the Global Minimum Tax (Pillar Two) Order 2024 — gov.im
- Isle of Man Government, Income Tax Division — National Insurance rates and thresholds — gov.im
- Isle of Man Government, Income Tax Division — National Insurance Holiday Scheme — gov.im
- Isle of Man Treasury — Budget 2026 measures and effective dates — gov.im
- Isle of Man Customs and Excise — VAT rates and registration — gov.im
- Isle of Man Customs and Excise — gambling duty rates — gov.im
- Isle of Man Government — rates valuation and local authority property rates — gov.im
- Isle of Man Government, Income Tax Division — double taxation agreements and TIEAs — gov.im
- Isle of Man Treasury — Manx currency, coins and notes (parity with sterling) — gov.im
- Council of the European Union — EU list of non-cooperative jurisdictions for tax purposes, updated 17 February 2026 — consilium.europa.eu
- Bank of England — daily spot exchange rate, US dollar into sterling — bankofengland.co.uk
- European Central Bank — euro foreign exchange reference rates — ecb.europa.eu
USD figures are indicative conversions at ~1 GBP = 1.35 USD (Bank of England daily spot rate, 10 September 2026) and rounded. Euro figures are converted at ~1 EUR = 1.16 USD (European Central Bank reference rate, 11 September 2026). The Manx pound is issued by the Isle of Man Treasury and is equivalent in value to pound sterling, so every £ figure in this guide is the same amount in sterling.
Last verified: 12 September 2026.
This is general information, not personal tax or legal advice. Tax outcomes depend on your specific facts; consult a qualified Isle of Man tax adviser before acting.
Related guides: Andorra · Argentina · Australia · Bahamas · Botswana · Brunei · Bulgaria · Ceuta and Melilla · Chile · China · Costa Rica · Cyprus · Denmark · Dominican Republic · El Salvador · Estonia · Florida · Georgia · Gibraltar · Greece · Hawaii · Hong Kong · Iceland · Indonesia · Italy · Jersey · Kuwait · Latvia · Macau · Malta · Mauritius · Monaco · Montenegro · Morocco · New Zealand · Panama · Paraguay · Philippines · Portugal · Puerto Rico · Romania · Sark · Seychelles · Singapore · South Korea · Taiwan · Thailand · Ticino · UAE · Uruguay · Zug